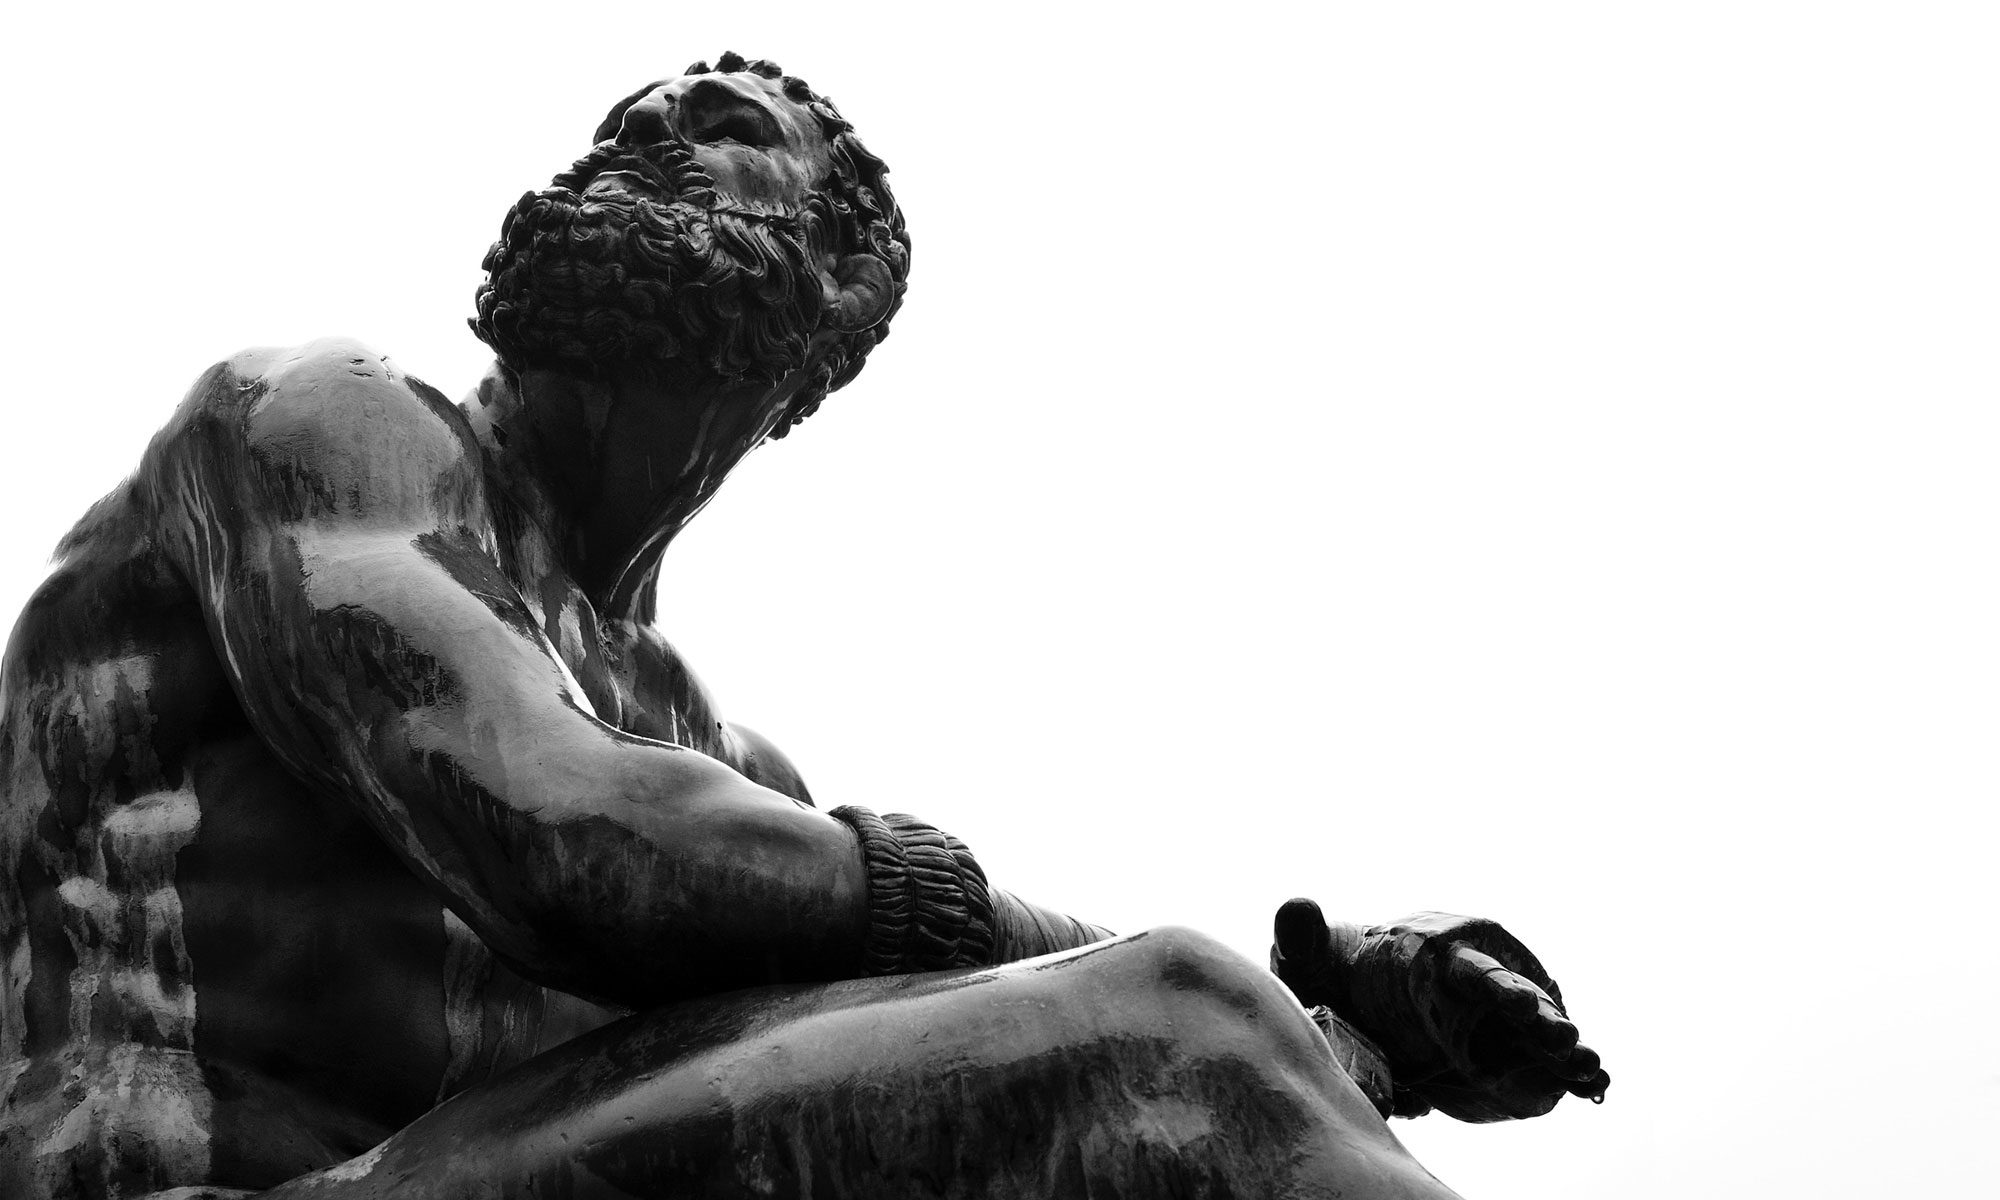
What’s with the Statue?

The Seated Boxer, an iconic ancient Greek work of art, shows a grizzled veteran of the ring, equal parts resigned and ready to spring into action. 

What I like is a sense of respite from competition, the powerful athletic physique and the tiredness that surrounds his humanity.  Is he a winner this day? Are there more fights to go?  How will his efforts be remembered?

These are questions that all of us encounter, in literal or figurative ways, in our daily efforts. 

Continue reading “What’s with the Statue?”

How CEO’s Succeed, or Not, in Different Organizations

Sometimes a leader’s career background is not a valid  basis for how they will perform in a new organizational environment.

Ed Callahan, who had multiple careers, observed that people will do what they know when moving from one career path to a new industry.

Callahan had three extraordinary leadership accomplishments.  First as a math teacher, coach and then principal and superintendent in the private Catholic school system.  Next as a leader in state government as Director of the Illinois Department of Financial Institutions followed by Chairman of NCUA.

After cofounding Callahans, he became CEO at Patelco Credit Union for 15 years. In that tenure the credit union moved from the 34th largest to 10th in total assets–all from organic growth.

His success in these diverse  leadership roles depended on his skills as an administrator. But that approach required the ability to motivate individuals  internally and externally.

I believe his success grew out of his initial years as a teacher and educator. Eleanor Roosevelt stated:  the secret to education is respecting the pupil.  Ed’s favorite phrase when setting credit union priorities was, “It is all about the member.”

Credit Unions Hiring Ex-Bankers

When credit unions bring ex-bankers into leadership positions,  they generally get a banker’s mentality in a coop suit. Priorities become financial performance, growth, and ultimately acquisitions  to expand. These efforts  become the ends versus the means for improving member-owner value. The focus is on institutional success not member return or community loyalty.

These approaches are not just alternate business models. They also reflect a market culture and values for which coops were supposed to be an alternative.  Now we see the coop system adopting the incentives of capitalism–but absent the market discipline stock owning shareholders demand.

A Military Leader in a New Role

Following is an example in which a person who reached the top of his profession in one critical era transferred his political skills into a different role.

America liked Ike, electing him President.  But his instincts as a political leader were also critical in leading the country in its domestic priorities.

President Dwight D. Eisenhower delivered his “Chance for Peace” (or “Cross of Iron“) speech on April 16, 1953, at the Statler Hotel in Washington, D.C., to the American Society of Newspaper Editors.  An excerpt from this former leader of Allied Forces in WW II:

“Every gun that is made, every warship launched, every rocket fired signifies, in the final sense, a theft from those who hunger and are not fed, those who are cold and are not clothed.  This world in arms is not spending money alone. It is spending the sweat of its laborers, the genius of its scientists, the hopes of its children.

The cost of one modern heavy bomber is this: a modern brick school in more than 30 cities.  It is two electric power plants, each serving a town of 60,000 population. It is two fine, fully equipped hospitals. It is some fifty miles of concrete pavement. We pay for a single fighter plane with a half million bushels of wheat. We pay for a single destroyer with new homes that could have housed more than 8,000 people.”

As a former five-star general, Eisenhower warned that an unending arms race drained vital resources from human needs.  As President, he became an advocate for civilian priorities versus military spending.  In an era of the Cold War and fears of communism and nuclear threat.

Leaders who easily  transition to new success in different organizations do so because they prioritize the needs of their members and constituents with shared purpose.  Private, public and civic institutions  are a means of serving others, not ends themselves

Credit unions are successful not because of institutional performance but how they serve member-owners and their community.  The key to  service is respect for the member, including their governance and the stewardship of their collective equity.


Leader Silence on Coop Merger Stampede

One of life’s  defining moments is being on the losing side.  It could be in a critical game, or competing in a local or national election, or the ultimate experience of war.

But when that happens there is an even greater loss.  That is  when one  realizes they were on the wrong side of events  in the first place.  Consider defeated political candidates who change parties or veterans who turn against the wars  in which they participated.

The Cooperative Merger Feeding Frenzy

The realization that one was on the wrong side from the beginning reminded me of the silent consent of industry leaders in the midst of the movement’s merger rampage.

Several commentators and I have publicly challenged the nonsensical proposal for SAFE to turn over the fortunes of its 245,000 member owners to Boeing Employees Credit Union.  An action members did not seek, was never discussed with them and was executed in secret with  a definitive merger agreement signed by both boards.

I was recently asked why  only retired industry leaders  openly discussed these chartering life or death decisions by hundreds of long-serving healthy credit union boards and their CEO’s.   This is an except of the observer’s concern:

An entire next generation (employees and leaders) wants to take action on this issue but can’t. They can’t even comment or like on LinkedIn without putting their jobs and careers at risk. 
This is the case from league leaders, external contractors to credit union staff.
That is why it’s almost entirely retired, or close to retiring, CEOs who are the public voice.
Is there a way to fund or create a group/website and have a channel for anonymous whistleblowing?

On The Losing Side

As the movement collapses upon itself led by the dark stars of merger advocates and gravitational pull of money, will  credit unions cohere into an  inert remnant in America’s financial universe?  Like the  S&L industry?

Current trends foretell a credit union singularity.  The end of the movement.

It would seem a question at the top of the agenda for those who want to lead  financial cooperatives into a worthwhile, sustainable future.  Why the silence?

A Missed Opportunity-or a New One Opening Up?

A little noticed outcome of the recent midterm elections was a ballot referendum in San Francisco.   The voters approved a municipal finance corporation that may seek a bank charter in the near future.

The full account can be found in this Next City article (link). The lead tells the story:

Proposition B created a municipal finance corporation that could potentially seek a bank charter in a few years. Meanwhile, Berkeley’s ballot measure to fund an East Bay public bank fell short.  

Now What?

This is just the beginning of a feasibility process to potentially seek a bank charter or other financial solution. But might a cooperative credit union be able to do much the same in helping manage public money and funding city priorities.

Could this be an opening for the credit unions operating in the Bay area to step up and say they want to be part of the appraisal process?

Public banking is not a new concept.  In North Dakota, the state owned bank, begun in 1919, has become  central to the state’s financial management,  working closely with  other financial institutions including credit unions.  (link)

The Opportunity: Innovate with a public-private partnership, or watch others take up the challenge?

Veteran’s Day 2026: The Call of Duty

Do you Know a Man Named Karl Marlantes?

That was the question my grandson, Emmett, texted from college.  I did not recognize the name.  He thought our paths might have crossed at some point.

His Wikipedia entry:  Karl Arthur Marlantes (born December 24, 1944) is an American author and Vietnam War veteran. He has written four books: Matterhorn: A Novel of the Vietnam War (2010), What It Is Like to Go to War (2011), Deep River (2019), and Cold Victory (2024).

This six minute Youtube video is a brief summary of his life as a Yale student, Rhodes Scholar and Marine Platoon leader, and his call of duty.  You would never suspect from his easy manner that he was awarded a Bronze Star, two Navy Commendation Medals for valor, two Purple Hearts, and 10 Air Medals.

The military draft caused generations of men to confront early in life, often as students, what duty means. Campus protests and military service are  two classic examples of how individuals answered what many knew instinctively-the call of duty.

The Control of Cooperative Capital

An observation by Ancin Cooley on one difference between cooperatives and bank business options:

A difference of Principle

Cooperative principles are best understood and upheld when juxtaposed against capitalist principles. “Growth” and “scale” are core tenets of a capitalist frame. A credit union could shrink from 100,000 to 10,000 and still meet the goals of its mission. However, a bank with investors could not do the same and call itself successful.

We can dance around it all day. The core issue at the center of the credit union movement is who’s going to control member capital.

As I check the scoreboard, those individuals bold enough to reach out and take control of these institutions through a variety of tactics are winning.

For the cooperative movement to survive, individuals must be given a reason or incentive to protect it.


SAFE’s Destruction Goes Far Beyond Concealing Vote Totals


A NOTE: The moral of the following  story may be transformational.  For the facts of this merger effort  are so absurd and anti-member, that the general public can easily see the cooperative crisis at hand.  If this event triggers an industry self-examination, then good news may result from this overt corruption of everything credit unions stand for.

In a democracy, the basic power of the people  over their leaders  is the right  to vote.

On October 27, member voting was closed at SAFE.  All the votes were in. But no vote totals have been announced after almost two weeks.

The elections were called, organized, controlled and managed by one side, that is the five senior managers and the board, seven of whom will directly benefit if the merger is approved. These seven, will be awarded over $15 million in bonuses on top of ongoing salaries and benefits.

Why have not totals been released?  The only answer is that the facts would undermine the narrative SAFE has been spinning about the merger.

The data gap could be as simple as the merger was turned down.  How do we announce that?

Or the vote margin was so narrow that requesting the regulator override the outcome would be inconsistent with protecting members’ best interests.

Of if the vote  showed 90-95% of members did not vote, then this participation failure would be light years away from the 50% required in state law.  This voting gap would demonstrates one  thing—that the credit union made zero effort to inform members about this life or death decision of their institution.  Instead they were counting on the auto response of a very few to follow the Notice’s plea to sppport their leaders into the abyss.

SAFE is like a defeated political party, in power, trying to figure out how to spin the  outcome in an election in which they controlled all the resources and messaging.  Low participation undermines any pretense of democratic accountability. It compromises the integrity of the credit union governance process.

Like authoritarian leaders in other democratic contests, SAFE’s incumbents are rigging the outcome to try to thwart both state law and members’ interests.

A merger would transfer over $440 million in capital for free to an organization that had zero role in generating it and gives  the owners $0 for their collective economic  interest.  Except for the seven insiders who helped themselves off the top.

A More Catastrophic outcome–The Exploitation of Member Owners

Credit unions had one simple approach to member value, what is good for the least  is good for all.  SAFE is the latest example of turning this cooperative principle upside down.  What is good for senior management. . . .

SAFE’s leaders are causing the worst kind of economic harm one can imagine to a credit union and its member-owners.

It is shutting down their 85-year independent charter, turning over a successful  locally focused $4.5 billion financial institution to strangers. SAFE  owners had no role in selecting and no information about BECU’s business model.  They know nothing about their future fate with BECU;s lwsweahip..

This  give-away is worse than financial theft.  The SAFE leaders are using their positions of trust and accountability to present an option that from  the latest data will cost them more for loans, pay them less for savings and require more in overhead expenses.

Cooperatives were supposed to be immune from this ever present human impulse to maximize personal gain from those you serve.

Credit unions are neither financial angels nor beasts, but in pretending to be angels, have become beasts.

Credit union mergers have devolved into cooperative theft organized by leaders in two organizations who show no capacity to distinguish  right from wrong.  It is the ethic of the bully, the powerful and those who gained positions of authority via democratic subterfuge

A Cooperative Odor is Spreading

The whole merger effort reeks from this mixture of  nonsensical financial proposition, the rhetorical propaganda of PR cliches, and the self-dealing of those entrusted with the stewardship of member-owner wealth.

This stench is spreading across credit union land, with individuals urging boards and CEO’s to get a good merger deal before it is too late.  That is before the public becomes aware and this widening  cooperative looting scheme is shut down.   SAFE’s  example, just one of many, will smear the entire good works, self-discipline and beneficial credit union conduct of those who refuse to play the game of beggar thy neighbor.

This industry cannibalization will stop only when credit union leaders who now plead for a common ground of unity move to a higher ground.  For it is not just SAFE, but the entire cooperative system that is operating with  this internal disease of self dealing corruption.

The financial liberty credit unions offered is not dependent on their special design and purpose, but rather the responsibility  each coop leader does or does not take.  Institutions won’t save us.  People will.

The Essential First Step

The minimal first step to curing this cooperative epidemic of self destruction is to reveal  how members voted in SAFE’s merger.   Why has this most fundamental practice of democracy been withheld?
 

“The Midterms” by Folk Singer Jesse Welles

Sometimes music can communicate reality more effectively than the spoken word.   For example,  Pete Seeger’s  anti war song, Where Have all the Flowers Gone?
Jesse Welles is a contemporary folk singer-songwriter and guitarist from Ozark, Arkansas.
He is a prolific and  powerful contemporary model of American folk protest songs. Armed with a guitar, a harmonica, and a gravelly voice described as sounding like “burnt toast.”
He is known for “singing the news.” He posts new DIY compositions almost weekly capturing the modern working-class struggle.  His words are biting as he sings about corporate greed and political hypocrisy.  He follows in the footsteps of Woody Guthrie and Bob Dylan.

His latest composition, The Midterms, has several trenchant insights, “Who would have ever thought Iran would go and change out our regime?”


These are the lyrics for those who did not catch all the satirical references.

I saw Elon leaving Austin, fat and hunchbacked, strange and pale. A half a billion dollar lesson that them Texans ain’t for sale. The ghost of Lindsey Graham came riding on a seven-headed drone. Flew right down to the golden golf cart, whispered, “Donald, listen close.”

“You can threaten civilizations, kill civilians, and just laugh. You can exterminate races, put folks into cages, but you just can’t mess with gas.” Mitch McConnell sat there speechless, but that’s kind of his new thing. Who would have ever thought Iran would go and change out our regime?

Oh, the eyeliner was running as JD watched the blue storm. He was swearing in the first jihadist to ever want healthcare reform. While that Temu Patton Hicks had crawled to Tennessee and begged, but the greatest military defeat in U.S. history had a hold of both his legs.

All the tech lords donned their banjos, their suspenders and craft beers, as they dusted off their pronouns, seeing that the end was near. And they wondered how they’d manage to destroy the planet first. They said, “What about China?” “China’s what about us? Always seemed a whole lot worse.” And the people said they did it, it’s a good start, sure enough. I’ve had the dream before, and my head’s still sore. But y’all should probably lawyer up.

Credit Unions and the Midyear Democratic Election Sweep

Elections really matter when voters believe they have been ignored by their chosen leaders,  whether these are elected in open contests or self-appointed  directors.

Historian and documentary film maker Ken Burns observed  a significant change in the what attracted voters’ support. He gave three contrasting pairings to show changes in candidates’ political appeals:

  • Not retribution, but restoration
  • Not hubris, but humility
  • Not self-dealing, but service

Burns explained that while the outcome had many “symptoms” such as  inflation, tariffs, corruption, and a broken political process—the core “disease” voters targeted was a rise in authoritarianism. A failure of democratic checks and balances.

He noted the American founders explicitly tried to “reverse engineer” the Constitution to prevent this kind of executive overreach.  The election results showed a collective desire to ressurect those original democratic safeguards.

What’s Ahead for Credit Unions

I think it is reasonable to believe that members will now be more interested in the ballot box, which is the credit union model of democratic self-governance.

I believe changes in Washington’s policy priorities for credit unions will emerge  in the new Congress if not within the administration. Following Burns’ analogy,  my three contrasting pairings would be:

Not deregulation, but democratic governance

Not financial performance, but fulfilling member purpose

Not consolidations, but collaboration

Several specific  thoughts:

  • NCUA’s single board member leadership will get greater scrutiny, regardless of the legal challenge to Trump’s firings. One impetus will be Congress seeking greater accountability for performance in those agencies Trump tried to dismantle or control.
  • There will be increased concern over consumer rights and renewed oversight by regulators.
  • Elections and voting are viewed as a critical aspect of member-owner democratic responsibility. This practice is frequently ignored by credit union boards in their annual meetings when filling director vacancies.  Board control versus member voting will become a more visible political issue. Especially in merger votes.
  • Growing and seemingly unstoppable federal deficit spending will put credit unions’ tax exemption on the federal fiscal agenda. Taxing the billionaires will apply not only to individual wealth but also to large, income-generating non-profits.  Are they meeting  their public purpose and duty?
  • Voters, as credit union members, become frustrated when they feel their leaders do not meet their needs or listen to their concerns.
  • Voting matters.  Americans have learned again that in democratic organizations this is the  means for change.

Voting is Empowering

Member voting is a healthy sign for cooperatives or any  organization which operates with rules and democratic accountability.   In cooperatives the member-owner design should be a competitive advantage versus those who want members only as customers.

Burns’ observation of the power of changing political appeals at the center of the midterms illustrates a common shared value.  Americans rejected the use of scapegoating, with references to  “THEM” and want leaders who focus on “US,” the collective well being.

Credit unions are at their strongest when the priorities are on the cooperative system of interdependence and member well-being. That is how the movement grew to  $2.6 trillion in assets.  Might that still be the best way forward together?

PS:  Speaking of voting, SAFE members are still waiting for the results from the  board’s efforts to merge with BECU.  Voting closed October 27.  Why have no numbers been disclosed?  What’s up?  This is not how democratic elections achieve legitimacy.  

Did SAFE’s CEO and Board Lose the Member Merger Vote?

Voting closed on October 27 for members to vote yes or no to merge with BECU.  That is five days ago.

There has been no SAFE announcement of results.  Nothing on the official merger home page https://www.safecu.org/combination/.    (safe.org/combination)

Nor could I find any press release or other update on SAFE’s website: https://www.safecu.org/.

Normally a credit union is quick to announce the results usually with general comments such has “members have overwhelmingly approved” etc.

But no vote totals announced.  No winner declared.  Is this because the vote did not go the way SAFE’s leaders hoped?  Are they now considering a plan B?

The Vote Numbers Are Critical

Without the numbers, we don’t know the election outcome.  Just as important is the total number  of votes cast.  In California  law a majority of members must vote in a merger decision for it to be approved.

However SAFE stated in the official meeting Notice they would ask for an exception to this requirement, regardless of the number of 245,000 members who participated.

In other words when following the law doesn’t work out, ask for an exemption to override this guardrail for member-owner democratic control.

A Faulty Merger Premise

This silence is a continuing example of the unilateral Board action to transfer all of SAFE’s resources, member relationships and legacy contributions over to another organization.   BECU is a Washington state charter whose main office is 750 miles away and operates under  different bylaws and business models from SAFE.  Members were told nothing about how BECU would change SAFE’s operations.

All merger efforts were done in secret without any member notice or dialogue. The only specific commitments in the merger agreement were to pay bonuses of up to $15 million to the five senior managers who arranged the merger. All the other employees were left to fend for their future if put in the  hands  of new leaders.

The Chair who signed the official Member Notice neglected to reveal she would receive one of the two $125,000 salaried director positions at BECU.   On October 22, five days before the final votes were due, a belated press announcement disclosed this arrangement

In analysis after analysis public posts at SECU-JustAsking and in my prior blogs, the public call report data showed SAFE members would pay more for loans, receive lower savings and have an overhead cost almost one-third larger under BECU control.

Why would members support closing their credit union, lose all independent operations and local control to pay more and receive less?

Next Steps

We may know the outcome of today’s political contests before SAFE reports the member voting totals.  Just another example of leaders ignoring their accountability to the owners. But the numbers will come out.

When that happens, the members and the regulators will have multiple decisions. If the vote is lost, that is a refutation of SAFE’s board and senior management.  Time for new leadership.

If the vote is de-minimis versus the legal majority standard, does SAFE just walk away or try to get a regulatory override?

Finally, what legal options can member-owners pursue to protect their rights and property interests in this credit union?

The vote numbers will just open another chapter in this misguided, self-serving effort to sell SAFE’s entire operations to another organization so seven leaders could make a quick buck.  And then letting  700 employees and 245,000 member-owners  fend for themselves.